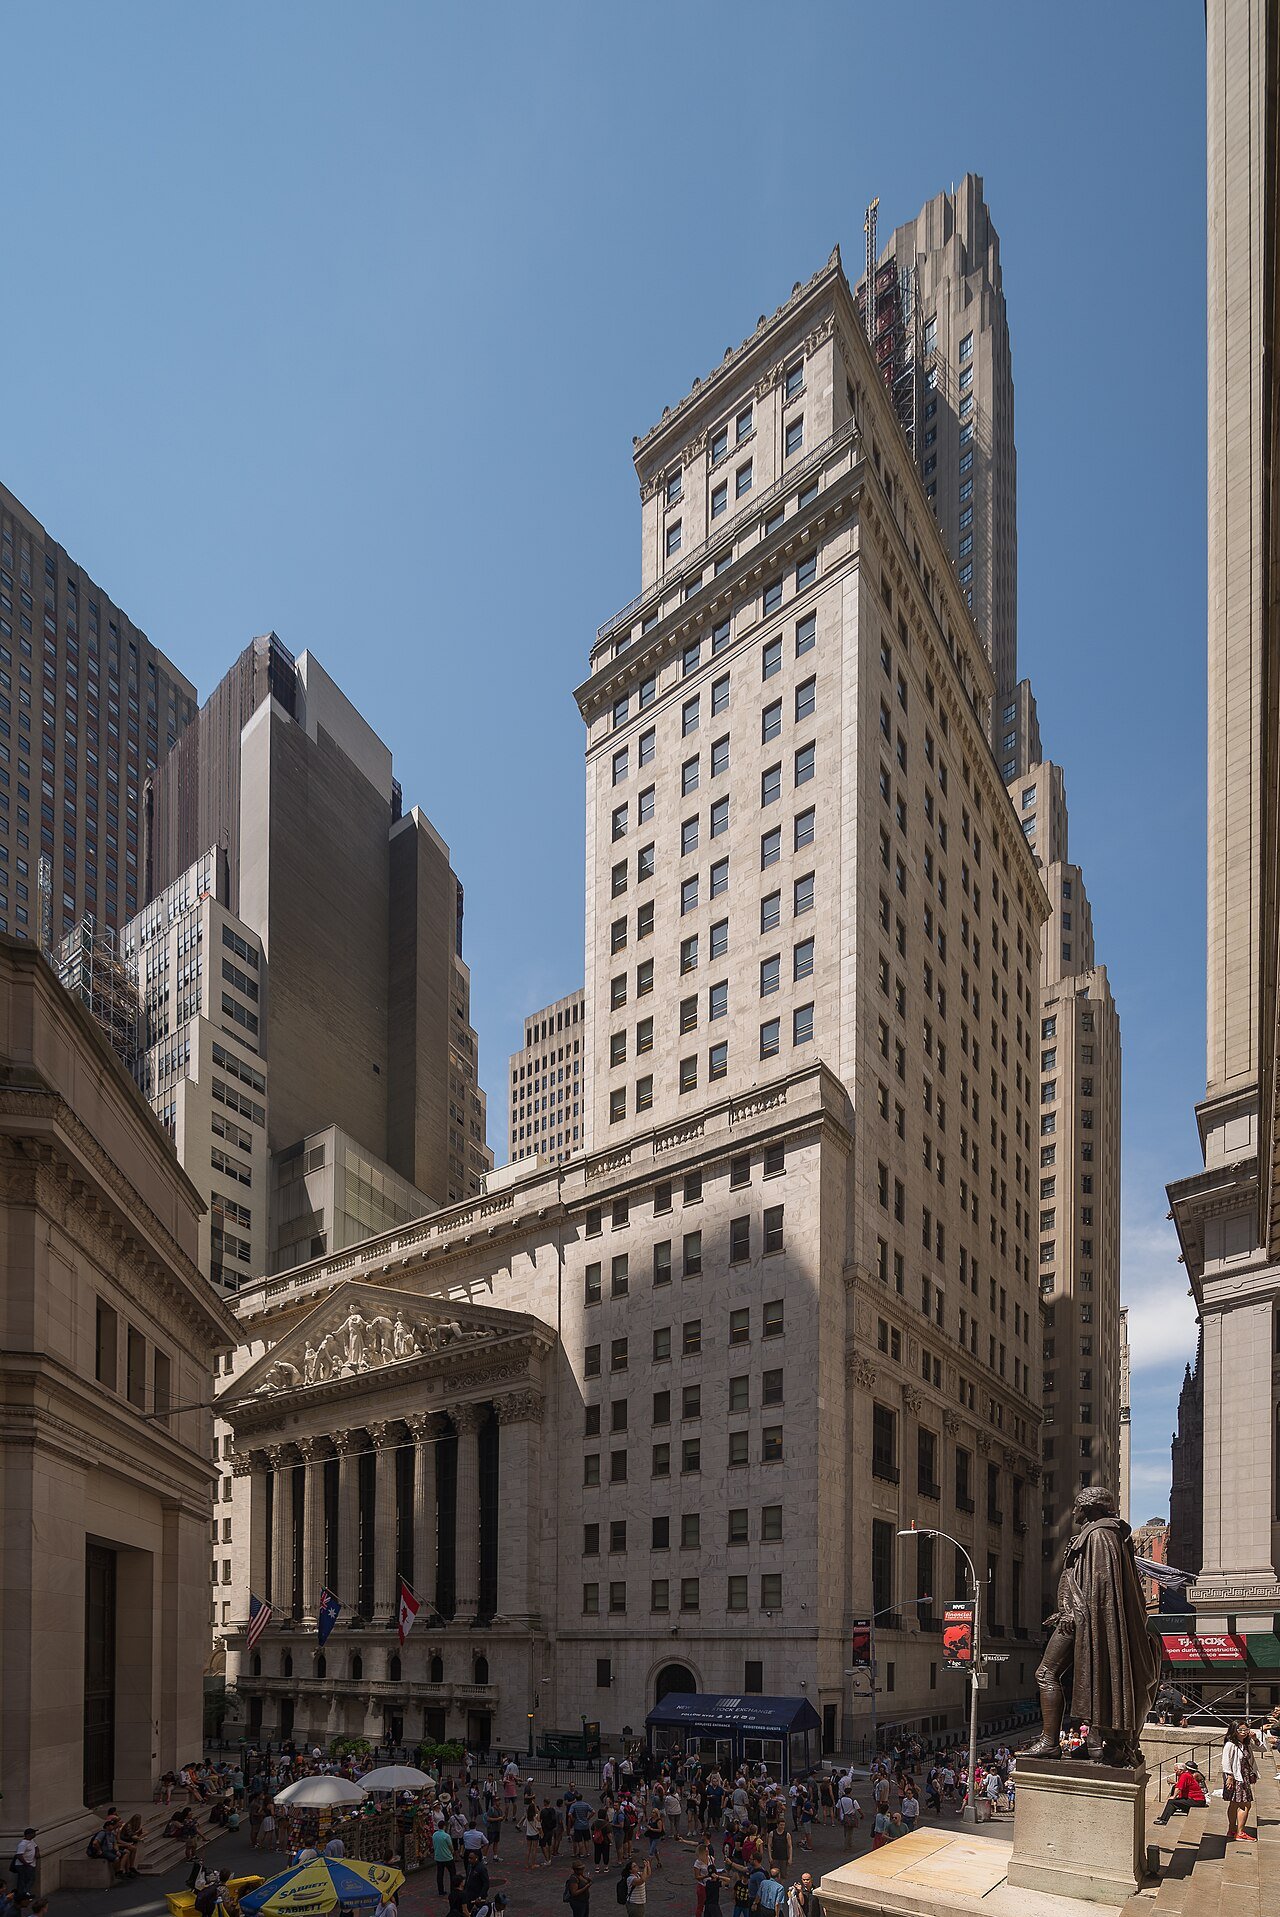
On October 6, 2026, Paramount Skydance completed its acquisition of Warner Bros. Discovery, and the combined company renamed itself Skydance Corporation, trading on the New York Stock Exchange under the ticker SKYD. The deal valued Warner at about $81 billion, or roughly $111 billion including debt. A century-old studio — the home of Bugs Bunny, Batman, and HBO — is now a subsidiary of a company controlled by the Ellison family. If you want a single date for the end of old Hollywood, this is a good one to pick.
The bidding war itself told the story. In December 2025, Warner's board agreed to sell its studios, HBO, and HBO Max to Netflix for $27.75 a share, a deal worth about $82.7 billion including debt, with the cable networks spun off separately. Three days later, Paramount went directly to shareholders with a hostile all-cash offer of $30 a share for the entire company, cable networks included, valuing it at about $108.4 billion. The board rejected it more than once, pointing to Paramount's credit rating and to more than $50 billion in new debt. Paramount kept raising, Larry Ellison provided a personal equity backstop reported at $45.7 billion, and the final offer reached $31 a share. On February 26, 2026, Netflix said it would not match, calling the deal no longer financially attractive. Warner shareholders approved Paramount's bid in April.
Notice what won. It was not the better streaming strategy or the more elegant corporate structure. Netflix offered a carve-out; Paramount offered the whole company, in cash, with committed financing and no financing condition. Paramount prevailed because it made its offer the easiest to accept — and because it had a billionaire willing to personally guarantee tens of billions of dollars. That is not a creative decision. It is a finance decision, and it is the kind of decision that now determines who owns the stories America watches.
The context makes it even clearer. Hollywood lost about 17,000 jobs last year, the domestic box office hovered around $8.9 billion — far below pre-pandemic levels — and production has been fleeing California. Meanwhile, Netflix, Apple, and Amazon now outweigh Disney, NBCUniversal, and Paramount in market value, and YouTube, which does not make content at all, is bigger in revenue and audience than any competing television platform. The studios did not lose to better movies. They lost to better distribution, better data, and vastly deeper pockets.
So what does the audience actually get? In the short term, probably more of the same: franchises, familiar intellectual property, and event films, because those are the assets that justify an $81 billion price tag. In the longer term, the question is whether a company built by a tech fortune will run a studio like a studio or like a library — an asset to be mined, bundled, and licensed. The 45-day theatrical window that Disney, Universal, and Paramount Skydance agreed this spring suggests the industry still believes cinemas matter. But belief is cheap, and debt service is not.
Hollywood has survived every disruption before it by becoming something else: silent to sound, studio system to blockbuster, broadcast to cable to streaming. This time the transformation is different, because the new owners are not really in the movie business at all. They are in the business of owning the pipes, the libraries, and the attention. The movies will go on. Whether Hollywood, as a place and a culture, goes on with them is now an open question.